Financing Communities.
We Map Every
Household.
From hidden cross-loan exposure to manual field collusion to unverified business use, we help MFIs uncover the household-level risks that basic KYC can't reveal. Because in microfinance, what's unmapped at the household level becomes the PAR you manage tomorrow.
Group lending fails when household risks stay hidden

Household Blindspots
Basic KYC and manual visits fail to reveal household composition, cross-loan exposure, and genuine borrower intent.

Unseen Overleveraging
Multiple loans across group members or shared households remain undetected without voter-based mapping.

Collusion in Field Checks
Manual verification allows officers to bypass checks for known borrowers, masking eligibility issues.

Weak Utilization Tracking
No proof of business use post-disbursal leads to diversion risk and stressed portfolio quality.
IDfy turns SME lending into a risk-proof advantage
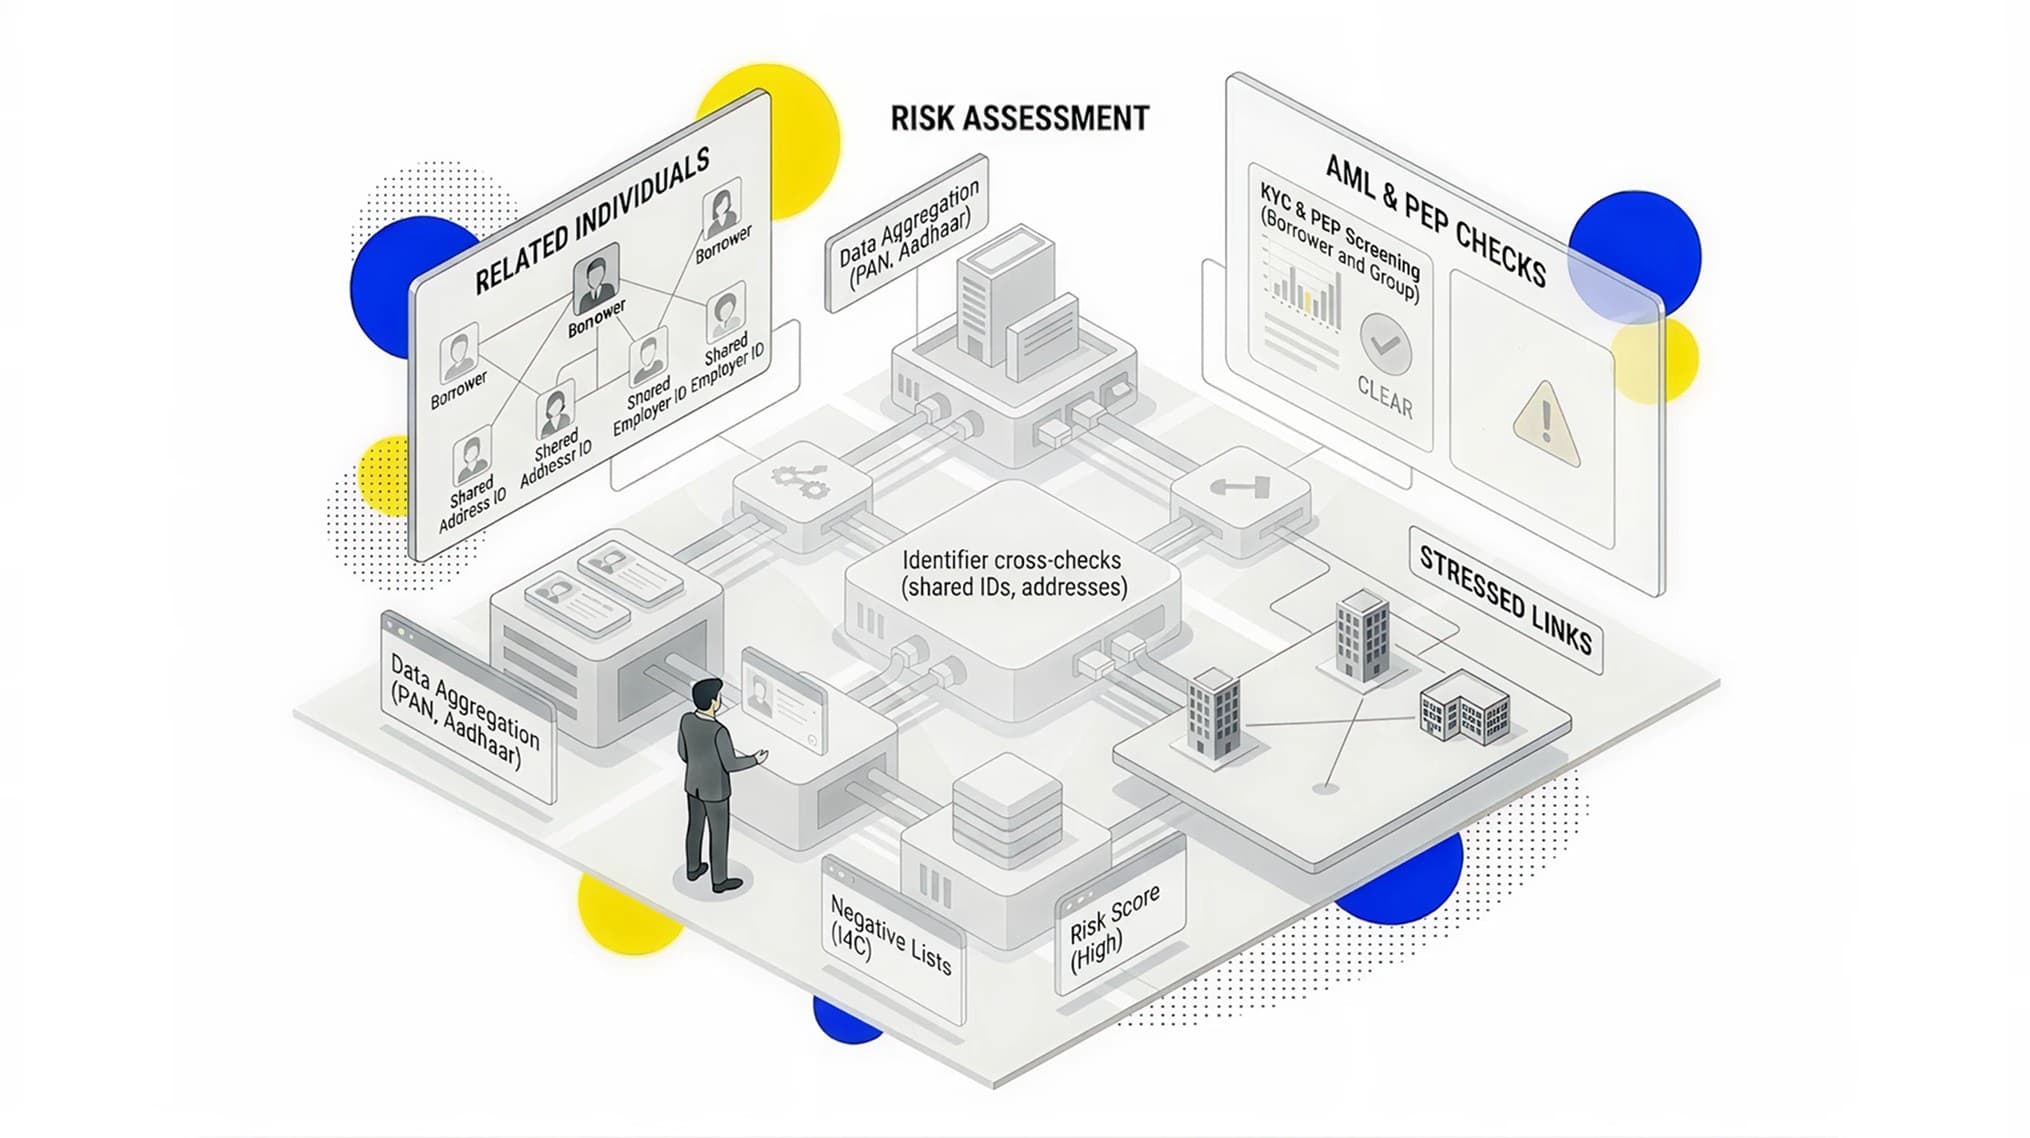
- Identify related individuals across addresses, shared IDs, and known high-risk relationships.
- Run AML & PEP checks at both borrower and group levels.
- Spot stressed households, shared vendors/customers, or high-risk links.
Why IDfy for microfinance

Household-level risk detected upfront to prevent hidden overleveraging

Reduced collusion via digital, geo-verified field visits

Verified loan utilization leading to stronger portfolio quality

Lower PAR & higher repayment rates through continuous validation
Trust at scale
Numbers don't lie. Neither do we.
Voice of the customers & awards
Kirti Patil
CTO

Abhinav Puneeth
Director


Sameer Jadhav
Vice President
Amarendra Nath Mishra
Group CHRO, Hero Enterprise
Devrat Singh
Senior Product Manager, Blackbuck
Kirti Patil
CTO
Abhinav Puneeth
Director
Sameer Jadhav
Vice President
Amarendra Nath Mishra
Group CHRO, Hero Enterprise
Devrat Singh
Senior Product Manager, Blackbuck
Kirti Patil
CTO
Abhinav Puneeth
Director
Sameer Jadhav
Vice President
Amarendra Nath Mishra
Group CHRO, Hero Enterprise
Devrat Singh
Senior Product Manager, Blackbuck